Can You Use a Mortgage for the Greece Golden Visa? Financing Rules Explained
Using a Greece Golden Visa with mortgage financing can be considered in some circumstances, but investors need to understand an important distinction: financing a property purchase is not the same as reducing the minimum investment required by the Golden Visa programme.
The property still needs to satisfy the relevant investment threshold, the qualifying purchase consideration must be fully paid, and the investor must obtain the required ownership rights.
For that reason, anyone planning to use borrowed funds should review the financing arrangement alongside the property purchase and Golden Visa requirements before committing to the transaction.
Is a Greece Golden Visa With Mortgage Financing Possible?
A mortgage does not automatically prevent someone from pursuing a Greece Golden Visa, but the way the transaction is structured matters.
Greek Golden Visa procedures require the qualifying real estate consideration to be paid in full using acceptable payment methods. The transaction must also result in the investor holding the ownership interest required by the relevant property-investment route.
This means there is a significant difference between:
borrowing part of the money while the seller receives the entire purchase price at completion, and
paying only part of the purchase price while leaving the remaining amount outstanding to the seller.
The first arrangement may involve external financing while still completing the purchase in full.
The second arrangement creates a much clearer concern because the qualifying consideration has not been fully paid.
Investors exploring the broader Greece Golden Visa programme should therefore have any financing structure reviewed before signing a binding purchase agreement.
Full Payment Is a Key Golden Visa Requirement
The central issue is not simply whether money has been borrowed.
What matters is whether the qualifying purchase has actually been completed according to the Golden Visa requirements.
Official Greek procedures require the agreed consideration to be fully paid and properly recorded through the notarial process. Payment must also be made through permitted and traceable channels.
Consider a simple example.
An investor buys a qualifying property for €400,000.
They use:
€250,000 of personal capital
€150,000 from a lender
€400,000 total paid to the seller at completion
In this example, the seller receives the full acquisition price.
Now compare that with an investor paying:
€250,000 at completion
€150,000 still owed to the seller over several years
The second transaction is fundamentally different because the full €400,000 purchase consideration has not yet been paid.
This is why the payment structure should be reviewed before the transaction is finalized.
Mortgage Financing Does Not Lower the Investment Threshold
A mortgage should not be viewed as a way to reduce the minimum Golden Visa investment.
The property itself must still meet the applicable threshold.
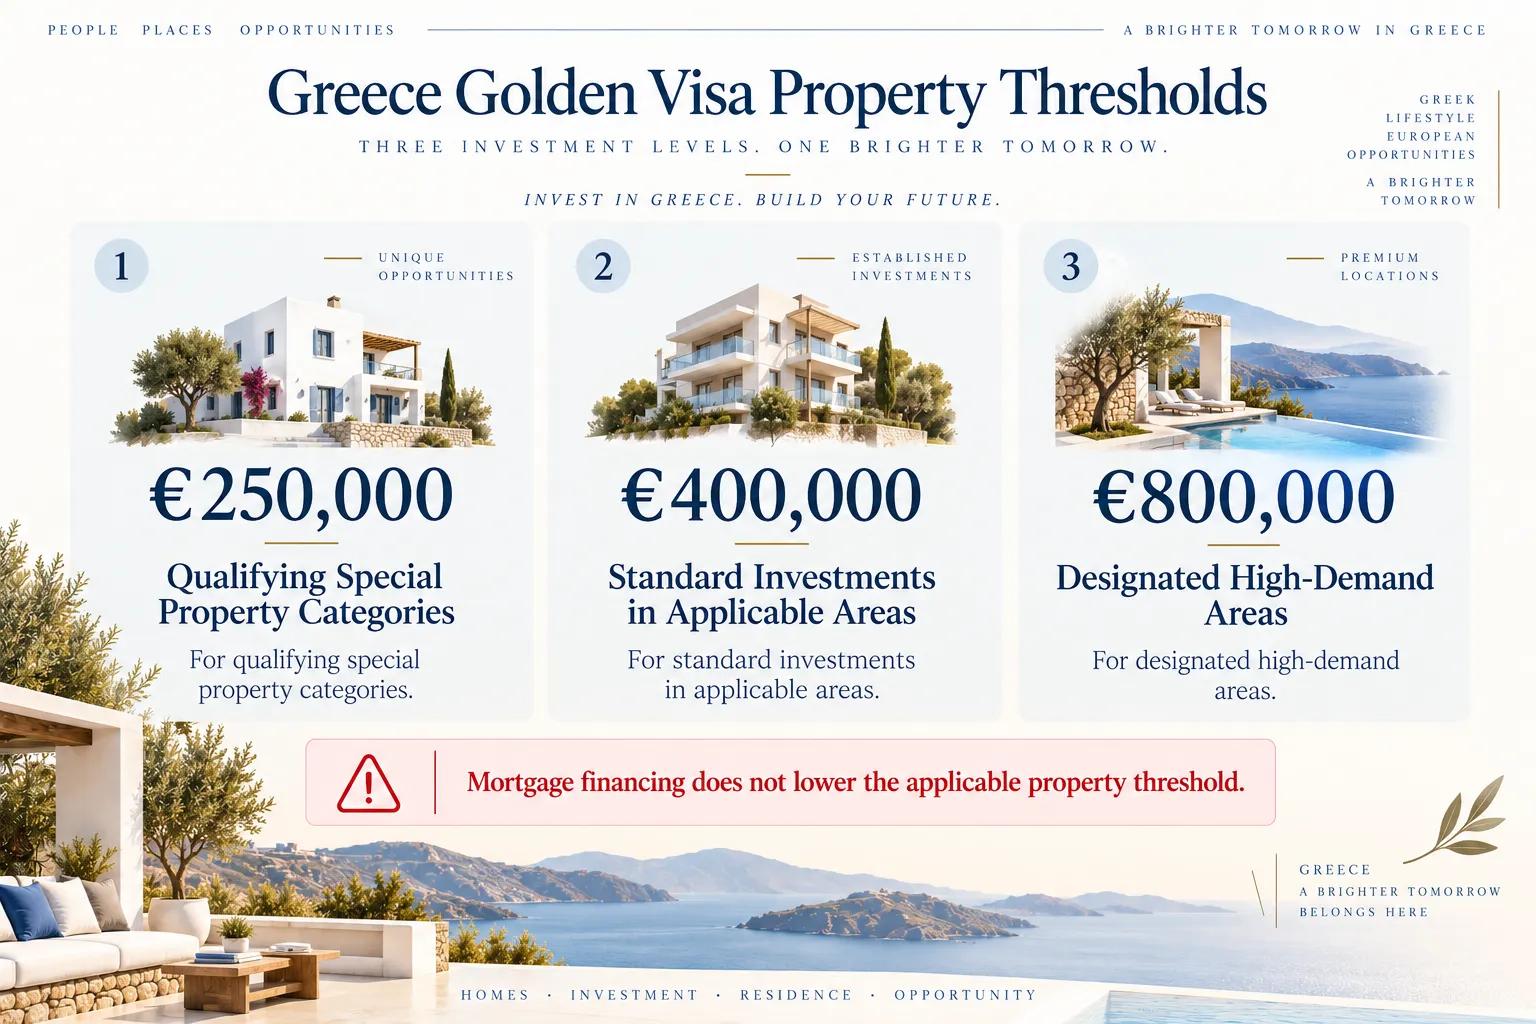
Depending on the location and investment category, current real-estate routes generally operate around three principal investment levels:

The qualifying transaction remains the €800,000 property acquisition.
The important questions are whether the seller receives the full consideration, whether the investor obtains the required ownership, and whether the financing and security arrangements are compatible with the intended Golden Visa application.
Investors can also review available Greece Golden Visa properties while assessing which assets fit their investment level and financing strategy.

Final Thoughts
A Greece Golden Visa with mortgage financing should be viewed as a way of funding a qualifying acquisition, not as a method of lowering the programme's investment requirement.
The property still needs to meet the relevant Golden Visa threshold, the qualifying consideration needs to be fully paid, and the ownership and transaction documentation must satisfy the applicable rules.
Borrowed funds and unpaid purchase consideration are not the same thing. An investor may potentially use financing while still ensuring that the seller receives the entire purchase price, but the particular loan and security structure should always be reviewed before completion.
For investors considering Greece alongside other international residence and citizenship programmes, Level Immigration provides guidance on residency and investment-migration options across multiple jurisdictions.
Does a mortgage reduce the €800,000 or €400,000 investment requirement?
No. Financing does not reduce the applicable property threshold. The property acquisition itself still needs to meet the required investment value.
Can I use borrowed money for the entire Golden Visa investment?
The important issues include full payment, qualifying ownership, the investment category and proper documentation. Because financing structures differ, investors should obtain legal and notarial confirmation rather than assuming that every fully financed transaction will qualify.
Can I get a mortgage from a Greek bank as a foreign investor?
Foreign investors may apply for Greek mortgage financing, but lending decisions are made by individual banks based on their own requirements, including financial position, income, creditworthiness and property valuation.
Does mortgage approval guarantee Golden Visa approval?
No. A mortgage is a banking product, while the Golden Visa is an immigration and investment programme. A property can satisfy a bank's lending criteria without satisfying the Golden Visa rules.
Can I finance a €250,000 Golden Visa investment?
Potentially, but the property must first qualify for one of the specific €250,000 investment categories. Financing alone does not make a standard property eligible for the lower threshold.